Washington home loans, shopped across lenders for you.
Team Kristen compares FHA, VA, conventional, jumbo, USDA and self-employed programs from a network of wholesale lenders, then gets you a pre-approval that holds up when it counts.
Get pre-approved Estimate a payment
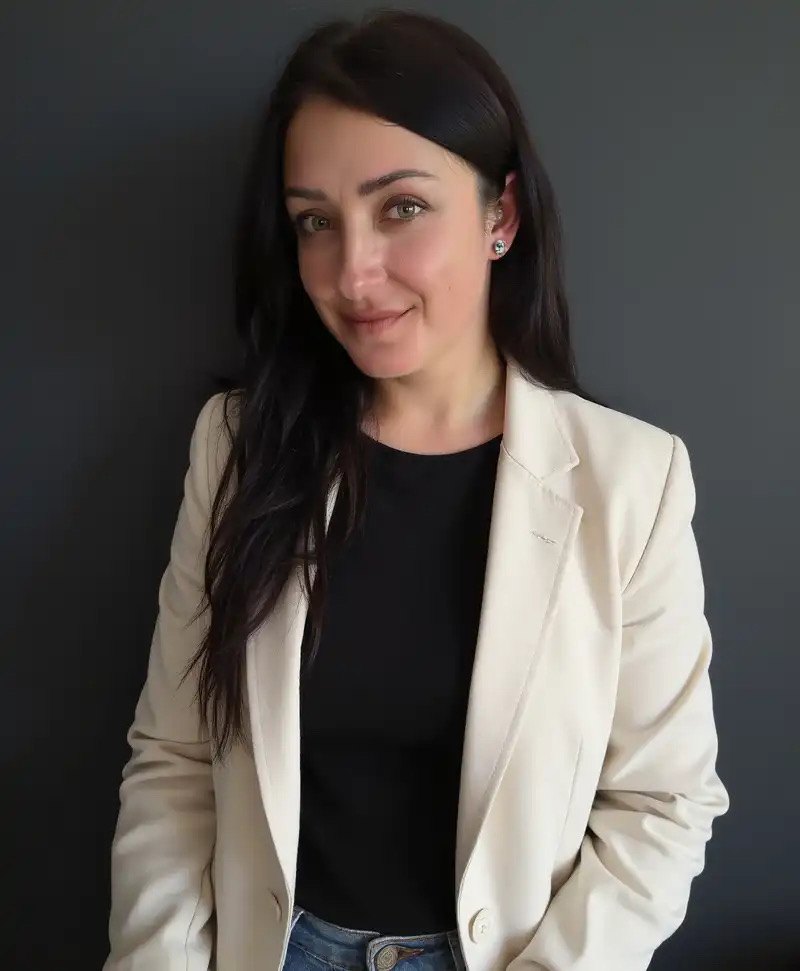
Kristen Hordyk, NMLS #2564353; Edge Home Finance, LLC, NMLS #891464. Licensed in Washington; serving all 39 counties. Meet Kristen
Where are you starting?
What clients say
Worked with Kristen? Your review helps the next Washington family find a loan officer they can trust.
Leave a reviewMortgage Loan Originator, NMLS #2564353
Edge Home Finance
Investor first. Mortgage broker second.
For the past decade, I haven't just financed real estate. I've lived it. I've spent 10+ years as an active real estate investor, flipping homes, operating rental properties and running profitable short-term rentals. I've been on every side of the transaction: the buyer, the seller, the landlord, the renovator, the strategist. That firsthand experience is why my clients don't get generic advice. They get guidance rooted in real numbers, real projects and real outcomes.
As a mortgage broker, I'm not restricted to one bank's box. As part of the Edge Home Finance team, I can shop 150+ lenders, which means I build financing around your scenario instead of forcing you into whatever a single lender offers. Whether you're buying your first home, refinancing, acquiring an investment property, scaling a rental portfolio or analyzing a flip, I bring the full market to the table so we can choose the lender, product and terms that serve your strategy.
- 10+ years investing: flips, long-term rentals and short-term rentals
- Access to 150+ wholesale lenders through Edge Home Finance
- First-time buyers, refinances, DSCR, portfolio and flip financing
- A vetted investor network: contractors, inspectors, property managers and more
Mortgage calculators
Plug in a rate you've been quoted. For your actual numbers, Kristen prices your scenario across lenders.
Estimated monthly payment
—
Estimated price range up to
—
Break-even
—
Break-even
—
DSCR
—
Estimate only, using the rate you enter. Not a rate quote, loan offer or commitment to lend. Actual rate, APR and payment depend on credit, loan program, property, loan amount and market conditions.
A broker works for your file, not a single bank's rate sheet
A bank can only offer its own programs. As a mortgage broker, Kristen submits your loan to the wholesale lender whose guidelines and pricing fit you, whether that's a 580-score FHA buyer, a self-employed owner with big write-offs or a Bellevue jumbo.
When one lender's guideline says no, another lender's often says yes. Matching your scenario to that lender is the job.
Loan programs
- Buy a homePre-approval, offer strategy and a loan matched to your budget, from first condo to forever home.
- RefinanceLower the payment, drop mortgage insurance, take cash out or consolidate debt.
- FHA loans3.5% down with a 580 score, flexible credit and gift-friendly down payments.
- VA loans0% down, no monthly mortgage insurance, for veterans and service members.
- Conventional loansFrom 3% down, with mortgage insurance you can remove later.
- Jumbo loansFinancing above the conforming limit, for Eastside, waterfront and luxury homes.
- USDA loans0% down in eligible rural and small-town areas.
- First-time buyersLow down payment programs, assistance and a plan from first call to keys.
- Down payment assistanceWSHFC and local programs that help cover the down payment.
- Self-employed loansBank statement, 1099, P&L and asset-based options when tax returns don't tell the whole story.
- Investor & DSCR loansQualify on the property's rent with DSCR, or use conventional investor financing.
From first call to keys
Talk it through
A short call about goals, timing and budget. No credit pull to start.
Pre-approval
Income, assets and credit reviewed up front, so your letter is real.
Lender match
Your file goes to the wholesale lender that fits it.
Close
Appraisal, underwriting, signing. Updates to you and your agent at every step.
Every corner of Washington
Seattle condos and Spokane starter homes, Kitsap VA purchases, Yakima USDA loans, San Juan Island second homes, Tri-Cities investors. Find local loan limits and program notes for your county.
Real estate agents
Underwritten pre-approvals, quick turn on updated letters, straight answers on tough files, and a loan officer who answers the phone on a Saturday offer deadline.
Questions people ask first
What does a mortgage broker do?
A mortgage broker compares loan programs and pricing from many wholesale lenders and arranges the loan with the one that fits. Kristen Hordyk is a licensed mortgage broker loan originator in Washington.
What areas does Team Kristen serve?
All 39 Washington counties, from Seattle, Bellevue and Tacoma to Spokane, Vancouver, the Tri-Cities, Bellingham, Olympia and rural communities statewide.
Is a broker more expensive than a bank?
Not inherently. Brokers are paid either by the borrower or by the lender, never both on the same loan, and compensation is disclosed on your Loan Estimate. Because wholesale pricing varies by lender, comparing several often lowers total cost.
What do I need to get pre-approved?
Typically 30 days of pay stubs, two years of W-2s (or tax returns if self-employed), two months of bank and asset statements, and a government-issued ID. Kristen sends a precise list after a short conversation.